
 Save time & money

Written by Michael Foote, Insurance Expert
Michael Foote is the founder of Quote Goat and has over 20 years experience working in finance & insurance. Since launching Quote Goat he has appeared on TV as well as many of the largest online publications including Forbes, The Telegraph and The Metro. Prior to Quote Goat, he worked in finance in the city.
Can You Combine Personal and Business Vehicles on Fleet Insurance?
Yes, but it depends on how the vehicle is used, who owns it, and what your insurer permits.
Fleet insurance covers vehicles used primarily for business purposes. Most insurers allow mixed-use vehicles (those used for both work and personal journeys) on a fleet policy. However, cars that never support business activities typically won’t qualify.
Understanding these distinctions helps you avoid paying for unnecessary cover or leaving dangerous gaps in protection.
What Qualifies as Business Use?
A vehicle qualifies for business cover when it’s regularly used for commercial activities, including:
- Visiting clients or suppliers
- Transporting tools, equipment, or stock
- Travelling between job sites
- Deliveries or courier work
- Commuting to your business premises
If your personal car performs any of these functions, it can usually join your fleet policy alongside vans, trucks, or other commercial vehicles. Business use must be the primary purpose, even if you also drive it for school runs or weekend trips.
Mixed-Use Vehicles: How They Work
Many sole traders and small business owners drive the same vehicle for work and personal trips. A van might carry tools during the week and furniture at weekends. A car might handle client meetings and family holidays.
As long as the vehicle is registered to you or your business and used regularly for work, most insurers will include it. You must declare personal use when applying. Failing to disclose this can invalidate your cover during a claim.
Some insurers offer specific mixed-use policies. Others require business mileage to outweigh personal use. Always check the terms before assuming both uses are covered.
What About Purely Personal Vehicles?
If a car is never used for business, most fleet insurers won’t cover it. They typically refuse to add vehicles that only handle school runs or social driving to a commercial policy.
Exceptions exist. Some providers allow directors or senior staff to add personal vehicles if they’re named on the policy and the insurer agrees in advance. This requires case-by-case assessment and may need proof of ownership or additional checks.
If you want all your vehicles on one policy for administrative convenience, speak to a broker. They can confirm whether it’s possible or if separate cover makes more sense.
Covering Different Vehicle Types on a Single Policy
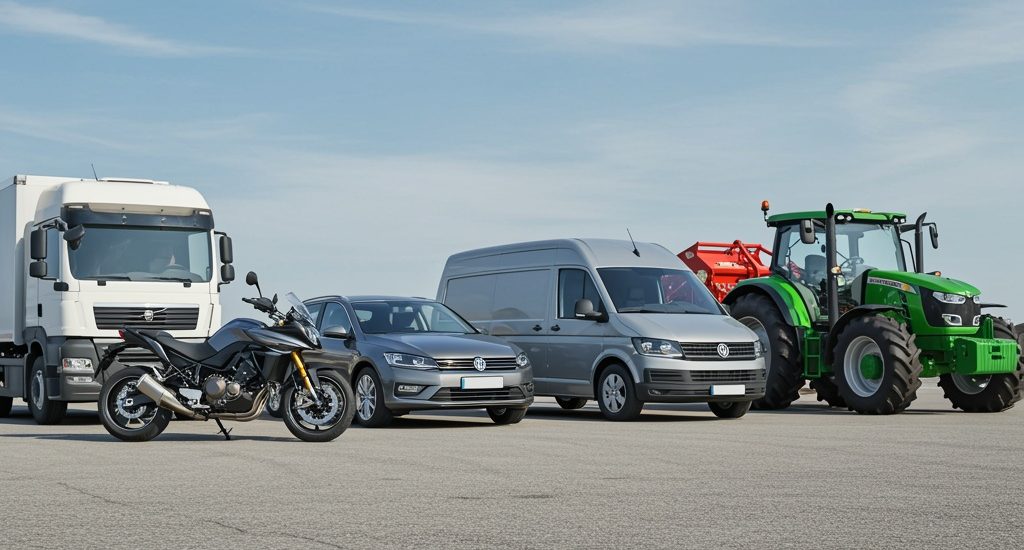
Fleet policies accommodate multiple vehicle types under one policy. You can typically insure:
- Cars
- Vans
- Minibuses
- Pick-up trucks
- Light commercial vehicles
- HGVs (depending on the insurer)
This flexibility suits businesses with varied needs, such as construction firms running vans and minibuses for crew transport, or consultancies managing multiple company cars.
For heavier goods vehicles, specialist cover may be required. Learn more about HGV fleet insurance.
Businesses with three to nine vehicles often benefit from mini fleet insurance, which offers tailored pricing and simplified administration.
How Insurers Price Mixed Fleets
Adding personal or mixed-use vehicles affects your premium. Insurers assess:
- How each vehicle is used
- Who drives it
- Annual mileage for business and personal use
- Whether it’s owned, leased, or financed
- Vehicle type and value
A high-value personal vehicle driven by someone with a poor claims history may increase your premium. Conversely, a low-mileage car used occasionally for business might have minimal impact.
Including personal vehicles may limit access to certain fleet-specific features:
- Tools-in-transit cover
- Goods-in-transit insurance
- Replacement vehicle hire tailored to commercial use
- Priority breakdown recovery
Understand what’s included before finalising your policy. For a detailed breakdown of costs, read our guide on how much fleet insurance costs in the UK.
Adding Vehicles Mid-Term
Fleet insurance allows you to add vehicles throughout the year. Whether you buy a new van, lease a car, or temporarily need an extra vehicle, most insurers let you adjust your policy mid-term.
Pricing is usually calculated pro-rata for the remaining policy period. Some insurers charge an admin fee; others include changes as standard.
If you’re expanding your fleet, check whether your insurer allows unlimited additions or caps the number of vehicles you can add between renewals.
Who Can Drive the Vehicles?
Fleet policies typically offer two driver options:
Named driver policies: Only listed individuals can drive
Any driver policies: Any employee or authorised person can drive, subject to age and licence restrictions
When mixing personal and business vehicles, ensure family members or personal drivers are correctly listed. Allowing an unlisted driver to use a vehicle can invalidate your cover.
For help deciding which option suits your business, read our guide on how to choose between named driver and any driver policies.
What You Must Declare to Your Insurer
Be transparent with your insurer about:
- How each vehicle is used (business only, mixed-use, or personal)
- Who owns or leases each vehicle
- Who will drive them
- Estimated business and personal mileage
- Any modifications or unusual features
Withholding information, even accidentally, can lead to rejected claims or cancelled policies. If you’re unsure whether a vehicle qualifies, ask before you apply.
When Separate Policies Make More Sense
Sometimes keeping personal and business insurance separate is better, especially if:
- Your personal vehicle has no business use
- You want personal no-claims protection
- Adding a personal car to a fleet policy costs more than standalone cover
- You prefer simpler, more tailored policies
For businesses with multiple vehicles used mainly for work, a fleet policy usually offers better value and convenience.
Get a Quote for Your Mixed Fleet
Every business has different needs. Whether you run a handful of mixed-use vehicles or a large commercial fleet, getting the right cover matters.
Use the quote form on this page to compare policies from specialist insurers who understand mixed fleets. You’ll receive tailored advice and no-obligation quotes that match your actual requirements.
