
 Over 110 car insurance providers

Written by Michael Foote, Insurance Expert
Michael Foote is the founder of Quote Goat and has over 20 years experience working in finance & insurance. Since launching Quote Goat he has appeared on TV as well as many of the largest online publications including Forbes, The Telegraph and The Metro. Prior to Quote Goat, he worked in finance in the city.
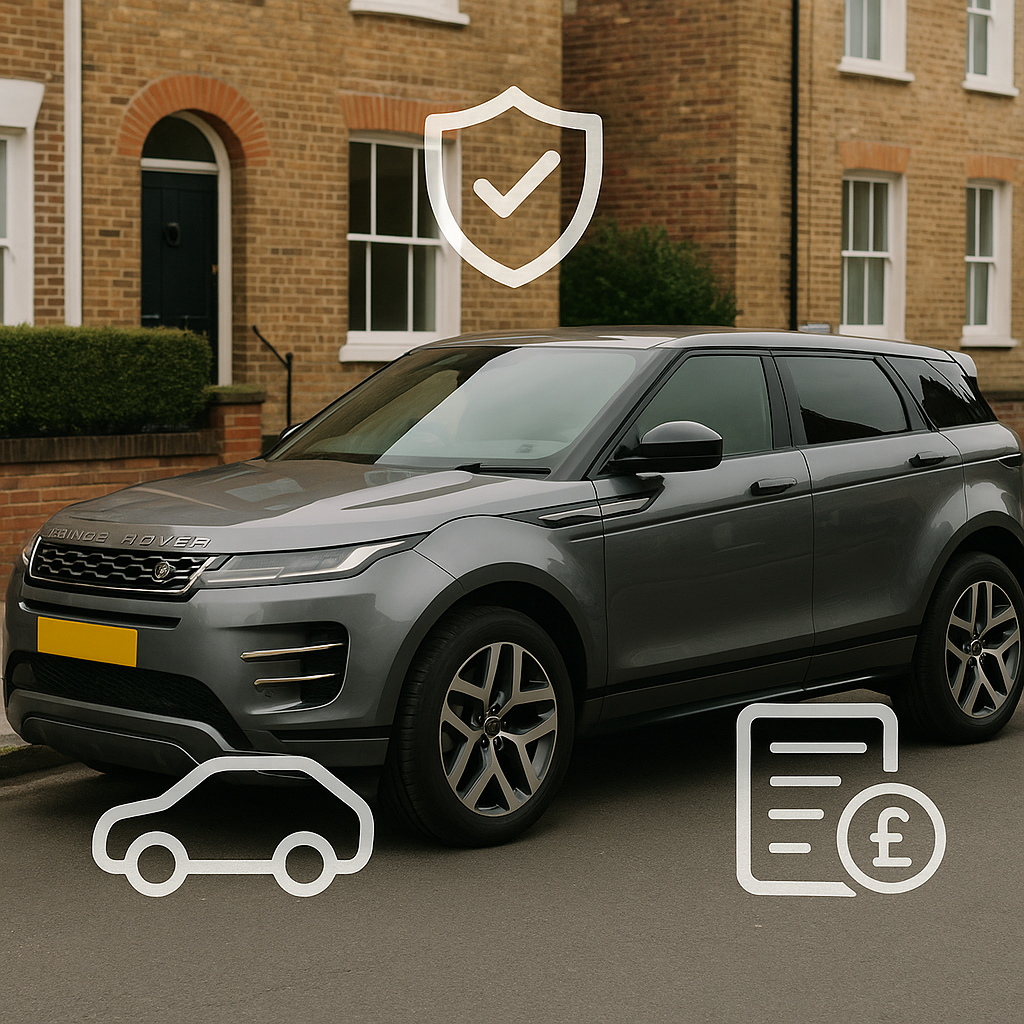
How Much Does Range Rover Evoque Car Insurance Cost?
The Range Rover Evoque is a popular compact luxury SUV in the UK, known for its distinctive styling and premium appeal. These qualities also make it more expensive to insure than many family cars.
Insurance costs for the Evoque vary based on several factors, but expect to pay anywhere from £600 to over £1,500 annually depending on your circumstances. Younger or newly qualified drivers may face significantly higher premiums, often exceeding £2,000.
The key reason for higher costs is the Evoque’s desirability, which makes it a theft target, combined with expensive parts and specialist repair requirements.
What Insurance Group Is the Range Rover Evoque?
The Land Rover Range Rover Evoque sits in insurance groups ranging from 24 to 40, depending on the model, engine size, trim level and year.
Entry-level models with smaller engines tend to occupy groups 24 to 30, while higher-spec variants with larger engines and additional performance features can reach group 40. These mid to upper groups result in higher premiums compared to mainstream hatchbacks or saloons.
Insurance groups are determined by factors including:
- Purchase price and replacement cost
- Repair costs and parts availability
- Performance and top speed
- Security features fitted as standard
- Likelihood of theft
To find the exact group for your Evoque, check your V5C registration document or use the Thatcham Research online tool.
Factors That Affect Your Evoque Insurance Premium
Beyond the insurance group, several personal and vehicle-related factors influence what you pay:
- Driver age and experience: Younger or less experienced drivers pay significantly more. Drivers over 40 typically benefit from lower premiums, as explored in our guide to Over 40 Car Insurance: What UK Drivers Should Know.
- Location: Urban areas with higher theft and accident rates, such as London or Birmingham, attract higher premiums. Rural postcode areas often cost less.
- Parking arrangements: Keeping your Evoque in a locked garage overnight reduces risk and can lower costs. Street parking increases premiums.
- Annual mileage: The more you drive, the higher the risk of a claim. Keep your declared mileage accurate but realistic.
- Claims history and convictions: A clean record and a no claims bonus reduce premiums. Previous claims or motoring convictions push costs up.
- Type of cover: Comprehensive policies may appear more expensive upfront but often provide better value, especially for higher-value vehicles like the Evoque.
What Type of Cover Do You Need?
You have three main options when insuring a Range Rover Evoque:
Comprehensive Cover
Covers damage to your vehicle and third parties in an accident, plus theft, fire, vandalism and windscreen damage. This is the most popular choice for Evoque owners given the vehicle’s value and the cost of repairs.
Third Party, Fire and Theft
Covers damage you cause to others and their property, plus protects your Evoque against fire and theft. It does not cover accidental damage to your own vehicle.
Third Party Only
The legal minimum, covering only damage to other vehicles and property. Rarely recommended for a premium SUV like the Evoque, as you’ll pay for any repairs yourself.
Given the Evoque’s market value and repair costs, comprehensive cover is usually the most sensible choice.
Optional Add-Ons Worth Considering
Many insurers offer additional features that may suit Evoque owners:
- Guaranteed replacement vehicle: Provides a like-for-like replacement if your Evoque is written off within the first year.
- Key cover: Covers the cost of replacing lost, stolen or damaged keys (often £300 or more for modern keyless systems).
- Breakdown cover: Gets you back on the road if your vehicle develops a fault.
- Legal expenses cover: Pays legal costs if you need to pursue an injury claim.
- Enhanced personal belongings cover: Protects valuables kept in your vehicle.
- Gap insurance: Covers the difference between your insurer’s payout and the original purchase price or finance settlement if your Evoque is written off.
Only add what you genuinely need. Check whether you already have cover elsewhere, such as through your bank account or home insurance.
How to Reduce Your Range Rover Evoque Insurance Costs
There are several practical ways to lower your premium:
- Increase your voluntary excess: Agreeing to pay more towards a claim reduces your premium, but make sure you can afford the excess if you need to claim.
- Improve security: Fit insurer-approved devices such as a Thatcham-approved alarm, immobiliser or tracker. Many insurers offer discounts for additional security.
- Limit your mileage: If you drive fewer miles than average, make sure your insurer knows. Lower mileage means lower risk.
- Add an experienced driver: Including an older, more experienced named driver can reduce costs, especially for younger policyholders. However, ensure the main driver is correctly declared.
- Build your no claims bonus: Each year without a claim earns a discount, often up to 70% after five years. Protect your bonus with an add-on if available.
- Pay annually: Monthly payments usually include interest. Paying upfront saves money over the year.
- Compare quotes: Prices vary widely between insurers. Always shop around before renewing.
What About Modifications and Business Use?
If you’ve modified your Evoque, even with manufacturer-approved upgrades like larger alloy wheels, upgraded sound systems or cosmetic changes, you must tell your insurer. Failing to declare modifications can invalidate your policy.
Similarly, if you use your Evoque for work purposes beyond commuting (such as client visits or deliveries), you need business use cover. Standard policies typically only cover social, domestic and commuting use.
Compare Range Rover Evoque Insurance Quotes Today
Insurance premiums for the Land Rover Range Rover Evoque can vary by hundreds of pounds depending on the insurer and the level of cover you choose. Comparing quotes ensures you get the right policy at a competitive price.
Use the button on screen to compare Range Rover Evoque insurance quotes tailored to your circumstances and start saving today.


